When you’re house hunting, the sticker price is just the start. The monthly payment is what you’ll live with for years. A mortgage calculator turns that big number into a realistic figure. But to get an accurate estimate, you need to know what to plug in. This guide walks you through each input, so you can avoid surprises at closing.
Why a Mortgage Calculator Matters
A mortgage calculator isn’t just a toy. It’s a reality check. It tells you if that dream home fits your budget. According to the Consumer Financial Protection Bureau (CFPB), nearly half of homebuyers don’t shop around for a mortgage. That can cost you thousands. Using a calculator helps you compare loan offers and see the long-term impact of interest rates.
Even a 0.5% difference in interest rate can change your monthly payment by over $100 on a $300,000 loan. Over 30 years, that’s more than $36,000. A calculator makes that visible before you commit.
The Key Inputs You’ll Need
Every mortgage calculator asks for a few basics. Get these right, and your estimate will be close to the real thing.
Loan Amount
This is the home price minus your down payment. If you’re buying a $400,000 house with 20% down, your loan amount is $320,000. But if you put down less than 20%, you’ll likely pay private mortgage insurance (PMI). That’s an extra cost many calculators include.
Interest Rate
Your interest rate depends on your credit score, loan type, and term. As of mid-2025, the average 30-year fixed rate is around 6.5%, according to Freddie Mac. A 15-year fixed rate is typically lower, around 5.8%. But rates change daily, so use current numbers.
Loan Term
Most mortgages are 30 or 15 years. A 30-year loan has lower monthly payments but you’ll pay more interest overall. A 15-year loan saves you interest but the monthly payment is higher. In practice, many buyers choose 30 years for flexibility.
Property Taxes
Your lender will collect property taxes as part of your monthly payment. The amount varies by location. For example, in Texas, the average effective property tax rate is 1.6%, while in Hawaii it’s 0.3%. You can find your county’s rate online or ask a local real estate agent.
Homeowners Insurance
Lenders require homeowners insurance. The national average is about $1,500 per year for a $300,000 home, according to Insurance Information Institute. That adds roughly $125 to your monthly payment.
PMI and HOA Fees
If your down payment is less than 20%, expect PMI. It usually costs 0.5% to 1% of the loan amount per year. If you’re buying a condo or townhome, you’ll also have HOA fees. These can range from $200 to $500 per month or more.
How to Use a Calculator Step by Step
Here’s a simple process to follow.
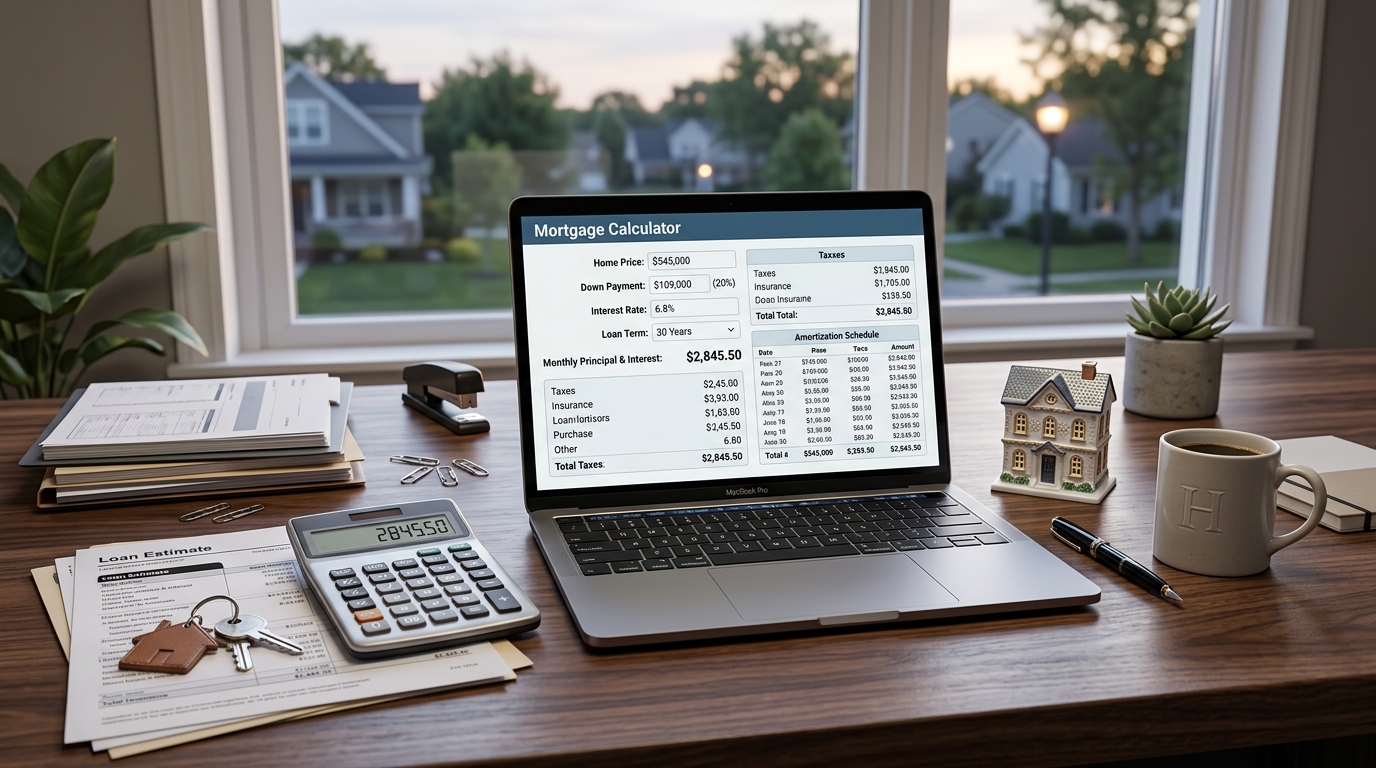
- Enter the home price and your down payment amount. The calculator will show your loan amount.
- Input the interest rate. Use a rate you’ve been quoted or the current average.
- Choose the loan term, usually 30 or 15 years.
- Add property taxes, homeowners insurance, and PMI if applicable.
- Hit calculate. The result is your estimated monthly payment.
But that’s not the end. You should also check the amortization schedule. This shows how much of each payment goes to principal and interest. In the early years, most of your payment goes to interest. For a $320,000 loan at 6.5%, your first payment of $2,023 has $1,733 going to interest and only $290 to principal.
That’s why making extra payments early can save you a lot. Even $100 extra per month can cut years off your loan.
Common Mistakes to Avoid
People often forget to include all costs. That’s the biggest mistake. A calculator that only shows principal and interest gives you a false sense of affordability. Always include taxes, insurance, and PMI.
Another mistake is using a rate that’s too low. Don’t assume you’ll get the best rate. Check your credit score and get pre-approved. In practice, a 0.25% difference in rate can add $50 to your monthly payment on a $300,000 loan.
Also, don’t ignore closing costs. They typically run 2% to 5% of the loan amount. On a $320,000 loan, that’s $6,400 to $16,000. While not part of your monthly payment, you’ll need that cash upfront.
Beyond the Basics: Advanced Tips
Once you have the basics, you can play with scenarios. What if you put down 10% instead of 5%? What if you buy points to lower your rate? Each change affects your payment.
For example, on a $400,000 home with 10% down, your loan is $360,000. At 6.5%, your principal and interest is $2,275. Add taxes ($500), insurance ($125), and PMI ($150), and your total is $3,050. If you put 20% down, you avoid PMI and your loan is $320,000. Your principal and interest drops to $2,023, and total payment is $2,648. That’s a $402 monthly difference.
Also, consider an adjustable-rate mortgage (ARM). A 5/1 ARM might start at 5.5%, but it can adjust after five years. A calculator can show you the initial payment, but you’ll need to estimate future payments. That’s riskier.
Using a Calculator for Refinancing
If you already own a home, a mortgage calculator can help you decide if refinancing makes sense. You’ll need your current loan balance, current rate, and new rate. Then compare the monthly savings against closing costs.
For instance, if you owe $250,000 at 7% and can refinance to 6%, your monthly payment drops from $1,663 to $1,499. That’s $164 saved per month. If closing costs are $5,000, it takes about 30 months to break even. After that, you’re saving.
But don’t refinance just for a lower payment. If you extend your term, you might pay more interest overall. A calculator can show you the total interest paid over the life of the loan.
Conclusion
A mortgage calculator is a powerful tool to estimate your monthly payment. But it’s only as good as the numbers you feed it. Include taxes, insurance, and PMI. Use realistic interest rates. And don’t forget closing costs. By doing your homework, you’ll avoid surprises and find a home that truly fits your budget. Start with a calculator today, and you’ll be better prepared for the biggest purchase of your life.
Q: What’s the formula behind a mortgage calculator?
Most calculators use the amortization formula: M = P [ i(1 + i)^n ] / [ (1 + i)^n – 1 ]. P is the loan amount, i is the monthly interest rate (annual rate divided by 12), and n is the number of payments (loan term in months). This gives you the principal and interest portion. Taxes, insurance, and PMI are added separately.
Q: How accurate is a mortgage calculator?
It’s accurate if you input accurate numbers. The principal and interest calculation is exact. But taxes and insurance are estimates. Your actual property tax depends on your local assessment, and insurance varies by provider. Also, PMI rates depend on your credit score. Use the calculator as a starting point, then confirm with your lender.
Q: Should I include property taxes and insurance in my monthly payment?
Yes, always. Your lender will escrow these costs, meaning they’re part of your monthly payment. If you don’t include them, you’ll underestimate your payment by hundreds of dollars. For example, on a $300,000 home, taxes and insurance can add $400 to $600 per month depending on location.
Q: What’s PMI and do I have to pay it?
PMI stands for private mortgage insurance. It’s required if your down payment is less than 20%. It protects the lender if you default. PMI typically costs 0.5% to 1% of the loan amount per year. You can avoid it by putting 20% down or using a piggyback loan. Once you reach 20% equity, you can request to cancel it.
Q: How do extra payments affect my mortgage?
Extra payments go directly to principal, reducing your balance faster. Even $100 extra per month can save tens of thousands in interest and shorten your loan term. For a $320,000 loan at 6.5%, adding $200 per month could save over $70,000 in interest and pay off the loan nearly 7 years early.
Article Was Generated By AI.