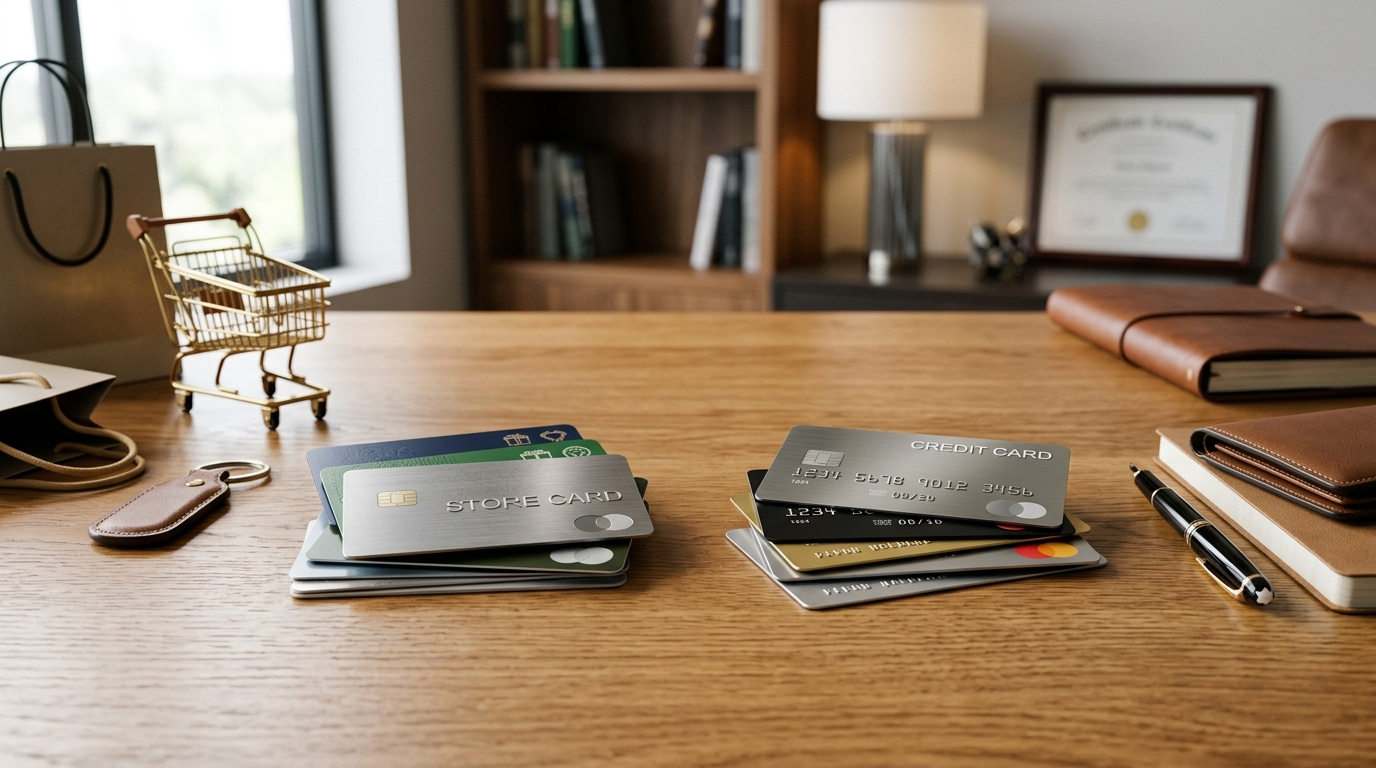
That 20% off offer at checkout can be tempting. But a store credit card is a very different animal from a regular Visa or Mastercard. Understanding the differences can save you hundreds in interest and protect your credit score.
What Exactly Is a Store Credit Card?
A store credit card works only at one retailer or a small family of brands. Think Target Circle Card, Kohl’s Charge, or the Amazon Store Card. You can’t use it at the grocery store or to pay your electric bill.
These cards often come with a sign-up discount. Macy’s, for example, frequently offers 20% off your first purchase when you open a card. That’s real money. But the trade-off is a high annual percentage rate (APR), often 25% to 30%.
Some store cards are closed-loop, meaning they work only at that specific chain. Others, like the Nordstrom card, are open-loop and can be used anywhere Visa or Mastercard is accepted. The distinction matters when you’re comparing offers.
Co-Branded Cards Blur the Line
Co-branded cards carry a retailer’s logo but run on a major network. The Costco Anywhere Visa is a classic example. You earn rewards at Costco and anywhere else Visa is taken.
These cards usually have better rates and rewards than pure store cards. But they still tie your rewards to one brand’s ecosystem.
Regular Credit Cards: The General-Purpose Option
A regular credit card from Chase, Capital One, or your local credit union works almost everywhere. You get one bill, one login, and one credit limit to manage.
Rewards on these cards are typically more flexible. You might earn 2% cash back on everything or 3x points on dining and travel. You can redeem for statement credits, direct deposits, or travel portals.
Interest rates vary widely. A good credit score can land you a card with a 16% to 22% APR. That’s still high, but often lower than store card rates.
Welcome Bonuses Can Be Huge
Regular cards often dangle big sign-up bonuses. The Chase Sapphire Preferred, for instance, has offered 60,000 points after you spend $4,000 in the first three months. That’s worth $750 toward travel.
Store cards rarely match that. Their sign-up perk is usually a one-time discount, not a ongoing rewards engine.
How They Compare: Rates, Rewards, and Fees
Let’s break down the key differences side by side.
- APR: Store cards average 26.5% according to a 2023 Bankrate study. General cards average around 20.5%.
- Rewards: Store cards offer 5% to 10% back at that retailer. Regular cards offer 1% to 5% back on rotating categories or everyday purchases.
- Sign-up bonus: Store cards give 10% to 20% off one purchase. Regular cards give $150 to $750 in cash or points.
- Fees: Store cards rarely have annual fees. Regular cards may charge $95 or more for premium rewards.
- Where accepted: Store cards work at one retailer. Regular cards work worldwide.
That 5% at Target sounds great until you realize you’re only earning it at Target. A flat 2% cash back card from Citi earns less per dollar but works everywhere.
The Math on Rewards
Suppose you spend $300 a month at a department store. A store card with 5% back earns you $15 monthly, or $180 a year.
A regular 2% card earns $6 monthly, or $72 a year. The store card wins here. But if you spread that $300 across multiple stores, the regular card wins.
In practice, most people don’t spend enough at one retailer to justify a store card unless they’re a loyalist.
Credit Score Impact: What You Need to Know
Both card types affect your credit score through payments, balances, and inquiries. But store cards can hurt more in subtle ways.
Opening a new card triggers a hard inquiry. That’s usually a 5-point dip, according to FICO. It stays on your report for two years.
Store cards often come with low credit limits. A $500 limit on a store card means your credit utilization spikes if you carry a balance. Utilization counts for 30% of your FICO score.
Regular cards tend to start with higher limits. A $5,000 limit gives you more breathing room.
Length of Credit History Matters
Closing a store card you’ve had for years can shorten your average account age. That’s 15% of your score. If you’re not using the card, keep it open with a small recurring charge.
Some experts recommend using store cards only for the sign-up discount, then paying them off immediately and sock-drawering them. That’s a valid strategy if you have the discipline.
When a Store Card Makes Sense
Store cards aren’t universally bad. They can work if you fit a specific profile.
You shop at one store frequently and pay your balance in full each month. You want a quick discount on a large purchase. You’re rebuilding credit and can’t qualify for a regular card yet.
Retailers like Best Buy and Home Depot offer store cards with promotional financing. You might get 12 months interest-free on a refrigerator. That’s a real benefit if you pay it off before the promo ends.
But if you carry a balance past the promo, the deferred interest can hit you retroactively. That’s a trap many people fall into.
Watch for Deferred Interest
Deferred interest isn’t the same as 0% APR. With deferred interest, you owe all the back interest if you don’t pay the full balance by the deadline.
On a $2,000 purchase with 26% deferred interest, that’s $520 in retroactive charges. Read the fine print before you sign up.
When a Regular Card Wins
Regular cards are the better choice for most people. They offer flexibility, better fraud protection, and often lower rates.
If you travel, a regular card with no foreign transaction fees saves you 3% on every purchase abroad. Store cards usually charge that fee.
Regular cards also come with perks like rental car insurance, extended warranties, and purchase protection. Store cards rarely match those benefits.
And if you ever need to dispute a charge, major issuers have more robust customer service than a single retailer’s credit department.
Building Credit with a Regular Card
If you’re new to credit, a secured card from Discover or Capital One is a better first step than a store card. You put down a deposit, get a low limit, and build history.
After 6 to 12 months of on-time payments, you can often upgrade to an unsecured card with better rewards.
Conclusion
Store cards and regular credit cards serve different purposes. Store cards offer tempting discounts but lock you into one retailer and often carry higher rates. Regular cards give you flexibility, better rewards, and stronger consumer protections.
Before you say yes to that checkout offer, run the numbers. If you pay in full and shop there often, a store card might work. Otherwise, a regular card is the smarter long-term move.
Q: Are store credit cards harder to get than regular credit cards?
Store credit cards are generally easier to qualify for, especially if you have fair or limited credit. Retailers often approve applicants with scores in the 600s. Regular cards from major issuers usually require good to excellent credit, typically 670 or higher. However, some premium store cards with co-branded networks may have stricter requirements.
Q: Can a store credit card help me build credit?
Yes, if you use it responsibly. On-time payments and low balances on any card, including store cards, get reported to the major credit bureaus. But store cards often have low credit limits, which can hurt your utilization ratio. A regular secured card might be a better credit-building tool for beginners.
Q: Do store credit cards charge annual fees?
Most store credit cards have no annual fee. That’s one of their main selling points. However, some co-branded cards, like certain airline or hotel cards, do charge annual fees in exchange for perks. Always check the terms before applying, because fees can eat into your rewards.
Q: What’s the average interest rate on a store credit card?
According to a 2023 Bankrate survey, store credit cards average a 26.5% APR. That’s significantly higher than the 20.5% average for general-purpose cards. Some store cards charge over 30%. If you carry a balance, the interest can quickly outweigh any sign-up discount you received.
Q: Should I close a store credit card I no longer use?
Closing a card can lower your average credit age and reduce your total available credit, both of which may hurt your score. If there’s no annual fee, consider keeping it open with a small recurring charge you pay off monthly. If you must close it, do so after you’ve built a longer credit history.
Article Was Generated By AI.